Funding Finder
Overview
Funding Finder matches borrowers with private lenders across short term debt, property development finance, and business term loans.
In this client project, my brief was to turn a manual loan application, run on emailed documents and spreadsheets, into a digital workflow that is quick and easy to use.
- Role
- Product Design Consultant
- Impact area
- Financial access
- Focus
- Discovery
- User Experience
- User Interface Detailing
- User Testing
Turning a lengthy application process into a guided, intelligent match

What borrowers said
“There are so many questions all at once. I just close the tab. I don’t have all this information in front of me.”
The problem
A borrower had to fill in a long paper application, and a broker had to chase them for whatever was missing.
Everyone pays for the same delay
When borrowers give up halfway, brokers spend the week chasing them.
- Borrower
67%of applications arrive incomplete
A borrower has to get through a long form before anyone tells them whether they qualify. Plenty of them close the tab and never apply.
“I don’t know if I even qualify.”
- Broker
40%of broker hours go to admin
Brokers can’t see where a deal has got to. They spend the week chasing updates from clients and lenders instead of advising anyone.
“Tracking deals across emails and spreadsheets means I’m always playing catch up with my clients.”
- Lender
3 to 6weeks from application to decision
Assessors get applications with information missing, or from borrowers who were never eligible. They read them all the way through, then decline them.
What success had to look like
- Completion
- 80%+Borrowers finish the application
- Time to apply
- <15 minBorrowers get from the first question to submitted
- Reached matches
- 70%+Borrowers get as far as a shortlist
- Abandonment
- ≤25%Borrowers who quit before the end
- Severity 3 and 4
- ZeroNothing unresolved before launch
- Confidence
- 4.0/5Rated by borrowers and brokers
Approach
Landscape review
User interviews
User journeys
Landscape review
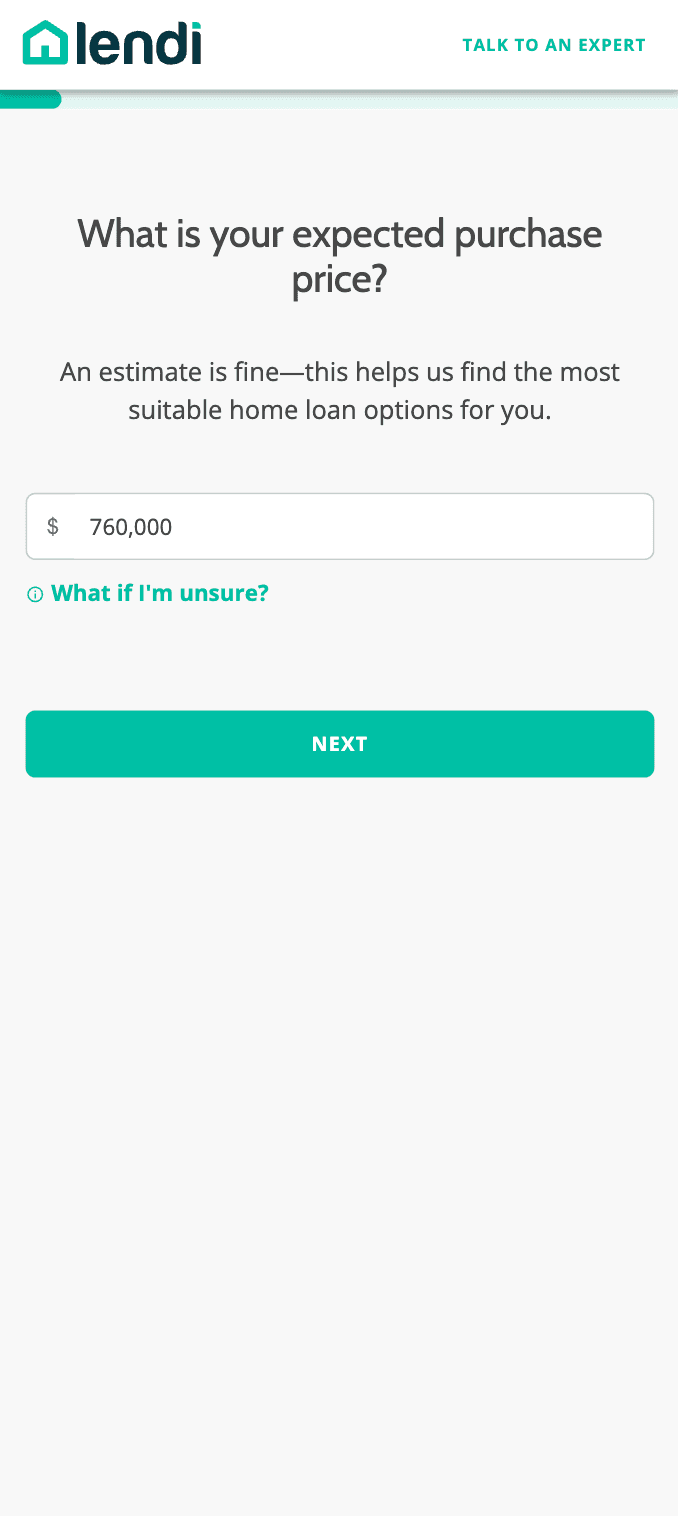
I reviewed three competitor products, and Lendi is the one shown here.
What worked
- One question per screen, with nothing else competing for attention
- No login and no account needed to begin
- Asks what the loan is for before any other question
- A “What if I’m unsure?” link on every question, for anyone without the exact figure
- What worked: One question per screen, with nothing else competing for attention; No login and no account needed to begin; Asks what the loan is for before any other question; A “What if I’m unsure?” link on every question, for anyone without the exact figure.
- The friction I noted: No way to save and come back, so a borrower who closes the tab loses everything.
- What I took forward: One question per screen, and no login to start; A count of questions left, shown from the first screen, so the effort is clear; A saved application, so a borrower can close the tab and pick it up later; Figures pulled straight from the borrower's bank, so nothing is typed from memory.
What worked
- One question per screen, with nothing else competing for attention
- No login and no account needed to begin
- Asks what the loan is for before any other question
- A “What if I’m unsure?” link on every question, for anyone without the exact figure
The friction I noted
- No way to save and come back, so a borrower who closes the tab loses everything
What I took forward
- One question per screen, and no login to start
- A count of questions left, shown from the first screen, so the effort is clear
- A saved application, so a borrower can close the tab and pick it up later
- Figures pulled straight from the borrower's bank, so nothing is typed from memory
User interviews
Form fatigue
“I give up halfway. I don’t know if I even qualify.”
Borrower
Long upfront forms made borrowers abandon the application before they saw a single match.
No shared source of truth
“My broker sends email attachments. I can never find the latest version.”
Borrower
A deal lived in two inboxes and a spreadsheet, so nobody could say what the current version was.
User journeys
“Help me find the right lender without wasting time on forms I might not qualify for.”
Discover
What they do
- Picks a loan type
- Short term, development or business
Where it happens
- Landing page
- Loan type selector
How it should feel
- Curious
- Discover. What they do: Picks a loan type; Short term, development or business. Where it happens: Landing page; Loan type selector. How it should feel: Curious.
- Apply. What they do: Answers one question at a time; Starts with no login; Reads why the question is asked. Where it happens: Progressive form; One question per screen. How it should feel: Confident.
- Link bank. What they do: Connects the bank account; Income and expenses pull through; No pages of manual fields. Where it happens: Bank connection; Consent and review. How it should feel: Reassured.
- Get matched. What they do: Gets a shortlist ranked by fit; Best match pinned to the top; Sees the reason it fits. Where it happens: Results screen; Ranked lender cards. How it should feel: Excited.
- Choose. What they do: Reads rate, term, monthly cost; Compares without opening a card. Where it happens: Lender comparison; Card layout. How it should feel: In control.
- Submit. What they do: Sends it to the chosen lender; Reads what happens next; Sees roughly when. Where it happens: Submission; Confirmation; Status tracker. How it should feel: Relieved.
Information architecture
- Screen
- Modal
- Menu
- Decision
- System
Choose a loan type
Short term debt, development finance, or a business loan
Navigation drawer
Products, how it works, broker log in
Bank connection
Pick a bank, and see exactly what will be shared
Connect the account?
Bank pulls through
Income, expenses and transaction history
Prefilled financials
Check what came back, correct anything
Skip for now
Type the figures instead
What we will ask you for
Question
One at a time, with progress shown
loop, until answered
Why is this asked?
The term in plain language, and what a lender does with it
Skip this one
Parked, and picked up again at the review
Review answers
Edit any answer, then come straight back here
Matching runs
Answers scored against every lender's criteria
Recommended lenders
Three ranked options, best match pinned, rate and monthly cost on the card face
My loan card
Full terms, what to prepare, and what happens next
Designing for borrowers
Designing trust into a faster private lending application.
Trust signals
Borrowers who link a bank account are worried about losing control of their money.
We explained what open banking sees and under that, borrowers read that the Australian Consumer Data Right protects their data and that they can cut off access whenever they want.
Usability testing showed this one screen raised trust and conversion.
- The Funding Finder prototype running on the open banking consent screen, headed “What open banking sees”, with a checklist of annual revenue, monthly expenses, cash and account balances, existing debt balances, and mortgage details and security property, then a lock panel saying the connection is read only and can never move money, and that the data is protected under the Australian Consumer Data Right so access can be revoked anytime.
Reduce drop-off rate
Linking a bank account fills the money questions in automatically so the form would be shorter.
The questions that are left come one at a time. A borrower makes one decision per screen, which feels lighter than a long form, so fewer people drop off.
In A/B testing, borrowers were 3× more likely to complete the application.
- The Funding Finder prototype running on the screen open banking has filled in. A green “Bank connected” badge names Commonwealth Bank, and six values sit under it: annual revenue $3,200,000, monthly expenses $148,000, existing debt $1,100,000, cash reserves $380,000, a security property at 22 Horizon St, Penrith NSW, and a property value of $2,800,000, each one editable before submitting.
- The Funding Finder prototype running on the first question, “What loan term are you looking for?”, alone on the screen with a line beneath it saying most private term loans range from 12 to 36 months, and four choices of 12, 18, 24 and 36 months.
Virtual card
A key design question was how to close the gap between approval and access to funds.
Virtual card disbursement via lenders’ existing Mastercard programs emerged as a promising direction worth exploring.


- A My Card screen in the Funding Finder prototype, running: the Funding Finder virtual card artwork, an available balance of $750,000, a type of Virtual Mastercard, and buttons to add the card to Apple Pay or Google Pay.
What testing changed
Plain language
Finance words went unexplained.
Terms like “security type” stalled borrowers in round 1, so I put one line of plain English under every question.
Before
Jargon, unexplained.
- A redrawn reconstruction of the earlier application form: one long screen headed “Loan application” with a Security section listing Security type, Net realisable value, Estimated property value and Loan to value ratio, then a Financials section, every label sitting bare above an empty box with no line of explanation under any of them, and the form still running on past the bottom of the screen.
- The Funding Finder prototype running on the security question: “Estimated value of your security property?”, with a plain-English line beneath it explaining that the security property is the one being offered as backing for the loan, and that the lender may order its own valuation.
Ranked matches
The matches were hard to tell apart.
Every lender read the same in a flat list, so I surfaced the metrics that separate them, ranked with the best match and its reason on top.
Before
A flat list to work through.
- A redrawn reconstruction of the earlier results screen, headed “Matched products” over the line “3 products match your details. Compare the options and choose one.” The same three lenders follow alphabetically, Apex Capital, Crest Finance and Meridian Fund, as identical bordered cards each listing rate, term, estimated monthly repayment and loan amount, with no best match, no match score and no reason given for any of them.
- The matched-lenders screen from the Funding Finder prototype, running: Apex Capital pinned at the top tagged Best Match at 98%, with the reason it fits — strong match on LVR, revenue and loan term — then Meridian Fund and Crest Finance ranked below it.
Designing for brokers
Replacing chaos with clarity through a broker dashboard.
One pipeline
Brokers ran their deals out of a spreadsheet and chased the rest by email.
I put the whole pipeline on one screen: every deal with its client, its amount, the fee it earns and the stage it has reached.
The stage filters carry their own counts, so a broker can pull up everything sitting at one stage without reading the list.
- The Funding Finder broker dashboard on its pipeline screen: summary cards reading 7 total deals, 4 active and 4 needing documents, a search field, a row of stage filters each carrying its own count, and the deal list beneath. Tanner Build & Co at $750K with a $15,000 fee is tagged App Submitted and high priority, Millbrook Properties at $1.2M is tagged New, Saville Hospitality at $480K is tagged App Submitted and urgent, and Aurora Medical Group at $320K is tagged Lender Offered.
One deal, one page
A deal is an application, a lender offer, a document trail and a conversation with the client.
I kept all four on the same page under tabs, with the amount and the projected fee held in the header so they stay in view wherever the broker is.
Documents carry their own state, so what is still outstanding is visible without opening anything.
- The broker dashboard on a single deal, Tanner Build & Co, with $750K and a projected fee of $15,000 held in the header beside an App Submitted badge. Four tabs run under it, Application, Offering, Messages and Status, with Application open on a grid of loan details: amount $750K, term 24 months, purpose business expansion, revenue $3,200,000, property value $2,800,000 and LVR 34%. The document checklist below opens with Tax Returns marked approved.
Where it stands
Every deal moves through the same seven stages, from new to settled.
The status tab lays them out as a timeline and marks the one the deal is on, so a broker can answer where things stand without asking anyone.
Stage carries an icon as well as a colour, so the badge still reads for anyone who cannot separate the tints.
- The Status tab of the same deal, showing the seven settlement stages as a vertical timeline: New, App Submitted, Lender Offered, Offer Signed, Valuation and Due Diligence, Final Terms and Settled. App Submitted is marked as the stage this deal has reached, and every stage carries its own icon as well as its own tint.
What testing changed
Undo
Closing a deal took one tap and no confirmation.
A broker closed a live deal by accident in the first review, so I put a confirmation on every destructive action, five seconds of undo on the result, and a different treatment on the actions that cannot be taken back.
Round 1 heuristic review. Nielsen #5, error prevention.
Before
One tap, no way back.
- A redrawn reconstruction of the deal screen as it stood before testing. Under the tabs, a Deal actions row offers Archive deal and Close deal as two identical grey buttons, either of which took effect on the first tap with no confirmation and no way back.
- The same screen after the fix. Close deal is drawn in red with a bin icon, set apart from the reversible Archive deal beside it, and pressing it raises a sheet headed “Close this deal?” saying Tanner Build & Co moves out of the active pipeline and that the broker can undo it for 5 seconds, with Keep it open and Close deal as the two answers.
Messages in the deal
There was no way to message a client from the dashboard.
Brokers texted and emailed instead, so the conversation sat outside the platform and never reached the deal history. I gave every deal its own thread, so a broker can send, track and refer back to messages without leaving it.
Round 2 usability testing. Nielsen #7, flexibility and efficiency of use.
Before
Nowhere to message the client.
- A reconstruction of the deal screen before the second round. Three tabs run under the header, Application, Offering and Status, with nowhere inside the deal to write to the client.
- The broker dashboard running on the deal's Messages tab: a note from Sarah Chen confirming no ATO debt and strong commercial property security at 34% LVR, the broker's own reply saying an updated P&L has been requested from the accountant, and an Add a note field with a send button beneath them.
The outcome
The platform shipped in three months, on time and under budget.
Achievements
- Delivery
- 3 monthsMVP launched on time and under budget
- Matching
- The progressive matching algorithm guided borrowers to relevant lending products, without surfacing options that did not suit their situation
- Borrower confidence
- By the end of usability testing, borrowers could confidently identify the right lender type for their needs
- Broker oversight
- The broker dashboard tested strongly for oversight and control. Brokers could immediately locate deal status, review client applications and identify what needed action